Ask two billing managers what it means to treat a patient “on a lien,” and you may hear the same phrase describing two very different documents. In California accident cases, providers often use letter of protection and medical lien to mean the same thing, yet the two rest on different legal ground and offer different protections. That gap matters, because it shapes how confident a practice can be about getting paid once a case finally resolves.
The distinction is not academic. A statutory lien draws its authority from a specific California law. A private agreement draws its authority from the strength of its own terms. Knowing which one applies to a given patient tells a provider what its recovery position actually is.
What a Statutory Medical Lien Actually Is
A statutory medical lien exists because the Legislature wrote a law that creates it. Two statutes do most of the work in personal injury cases:
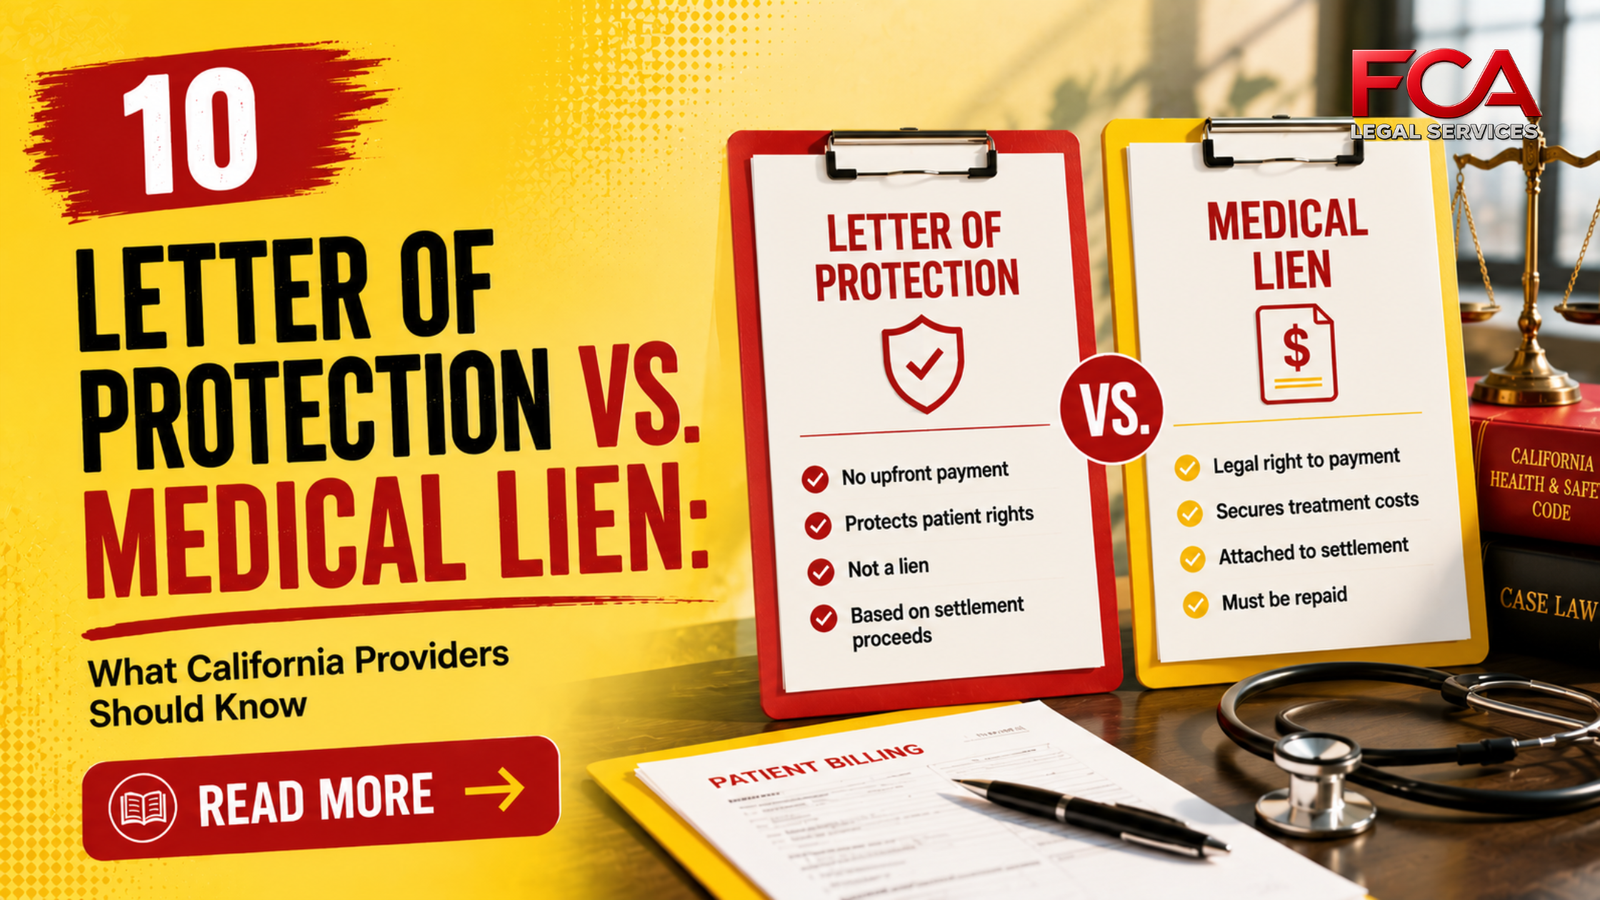
- Civil Code 3040 governs health care liens tied to care already paid for by a health plan or disability insurer. It caps how much such a lien can recover, generally tying the amount to what the insurer actually paid to provide the care rather than to full billed charges. It applies to a defined set of insurers, plans, medical groups, and independent practice associations, not to every provider.
- The Hospital Lien Act, found at Civil Code 3045.1 and the sections that follow, gives a licensed hospital a lien on a patient’s third-party recovery for the reasonable and necessary charges of emergency and ongoing care. It reaches hospital charges connected to an accident, and it does not apply to ordinary workers’ compensation claims.
The practical point is that these statutes have specific scope. Not every provider and not every kind of charge falls under either one automatically. A physical therapist, an imaging center, or an outpatient surgeon may not fit the language of either statute, even though the office still expects payment from the eventual settlement.
What a Letter of Protection Is, and Isn’t
A letter of protection, often shortened to LOP, is a contractual promise. It usually comes from the patient’s attorney and assures the provider that the practice will be paid from settlement proceeds once the case resolves. Practices rely on it to justify continued care when a patient cannot pay upfront, and a letter of protection for medical treatment can keep that care moving while a claim works toward resolution.
What an LOP is not is a statutory lien. It does not carry the automatic recognition that Civil Code 3040 or the Hospital Lien Act extends to the parties those laws name. Its strength comes from its own terms and from the reliability of the attorney who signs it, not from a statute written for this purpose.
That does not make it a weaker instrument. A well-drafted agreement with a dependable law firm can protect a provider effectively. It simply means the protection has a different source. Reading letter of protection vs lien as “informal versus official” misses the point. These are two mechanisms with two foundations, and each carries its own risk profile.
Why the Distinction Changes a Provider’s Risk Position
Because a statutory lien has a defined legal framework behind it, a provider who qualifies for one knows where to look when a dispute arises. The statute sets the boundaries. With an attorney’s letter, any disagreement instead turns on contract law and on the specific words in the agreement. If the language stays vague about priority, timing, or what happens when a case settles for less than expected, the provider absorbs that uncertainty.
This is a due-diligence issue, not just paperwork. Practices that lean heavily on these agreements benefit from clear, precise language and from working relationships with attorneys who honor their commitments consistently. Understanding how legal funding for medical facilities works can also help administrators see where a given patient’s charges sit in the payment chain. When the terms are strong and the relationship is solid, an LOP can be a reliable route to payment. When either is shaky, the risk climbs quickly.
Before accepting a letter of protection for medical treatment, a practice should read the agreement closely and know exactly who stands behind it. Providers should also confirm which document they actually hold. Some accident patients arrive with a hospital lien already in place, others with an attorney’s letter, and some with both, each covering different charges. Treating every arrangement as the same “lien” invites mistakes in how a practice tracks and pursues what it is owed.
What This Means for Reimbursement Timing and Amount
Both mechanisms share one hard limit: they depend on the case resolving with enough recovery to pay everyone. A statutory lien and an LOP each point to the same settlement fund. If the case loses, settles low, or stalls for years, neither one produces money that is not there. Statutory recognition affects priority and enforceability, but it does not guarantee full payment on its own.
This is where knowing your mechanism pays off, because the letter of protection vs lien question ultimately comes down to which document governs a given patient’s charges. A hospital operating under the Hospital Lien Act follows one set of rules on notice and priority. A clinic holding a private agreement follows the terms it negotiated. Recognizing how a medical lien compares with surgery funding helps a practice set realistic expectations about both timing and amount before assuming a collection path. Providers who map this out early avoid chasing the wrong remedy months later.
For practices that treat a steady volume of accident patients, the stretch between service and settlement creates real cash-flow strain. That pressure is one reason medical lien funding has become a common tool. It lets a provider access value tied up in pending cases sooner, rather than carrying every open receivable until each case closes.
What You Should Know
The core lesson is easy to state and easy to overlook. A statutory lien and a private attorney agreement are different instruments with different legal foundations, and one is not simply a lighter version of the other. A statutory claim draws on Civil Code 3040 or the Hospital Lien Act. A letter of protection draws on the strength of its own contract. Sorting out which one applies to each patient, and keeping the agreement language tight, protects a practice far better than treating the two as interchangeable. For your own forms and agreement wording, confirm the details with qualified legal counsel rather than relying on general guidance.
Fund Capital America works with California providers who treat accident patients and want steadier cash flow while cases resolve. Our medical lien funding and facility lien funding services help practices turn pending case value into working capital without waiting for every settlement to close.
Who is Fund Capital America?
Since 2006, Fund Capital America (FCA) has been a trusted leader in pre-settlement funding, providing cash advance loans to plaintiffs in personal injury and accident cases. Over the years, FCA has proudly served thousands of law firms and tens of thousands of clients, helping them navigate the financial challenges of litigation. While our core service is pre-settlement funding, we also offer a comprehensive range of services to support law firms and their clients from the beginning of the case to the final settlement check distribution.
Fund Capital America’s Services
In addition to pre-settlement funding, FCA provides a broad array of services designed to alleviate the financial and administrative burdens on injury victims, law firms, and medical professionals. Our services include:
- Pre Settlement Funding
- Policy Limits
- Doctor & Medical Facility Directory
- Doctor & Medical Facility Scheduling
- Language Services
- Investigation Services
- Medical Legal Finance
- Surgery Funding
- Medical Lien Funding
- Law Firm Funding & Law Firm Banking Services
- Law Firm Line of Credit
- Medical Receivables Financing
- Law Firm Services
Get the Legal Funding Support You Need in Just 5 Minutes!
Here’s how it works:
Fill out our application form: It takes just 5 minutes to provide the necessary details about your case.
Get prequalified: Our team will review your application and get back to you swiftly, often within hours.
Need assistance? Call us at the number provided for immediate support from our knowledgeable staff.
Don’t let financial stress prevent you from focusing on your recovery. Apply now to secure your lawsuit cash advance!